U.S. households are maintaining more video subscriptions while overall spending remains flat. For streaming providers, that combination makes pricing, advertising, and retention central to the next phase of competition.
Parks Associates research shows that 54% of U.S. internet households subscribe to five or more SVOD services. Among subscribing households, the average number of pay-TV and SVOD subscriptions increased from 6.3 to 6.7 between Q1 and Q3 2026, while monthly spending remained approximately $113 per month.
Consumers continue to value access to multiple services. Their willingness to increase total spending is more limited.
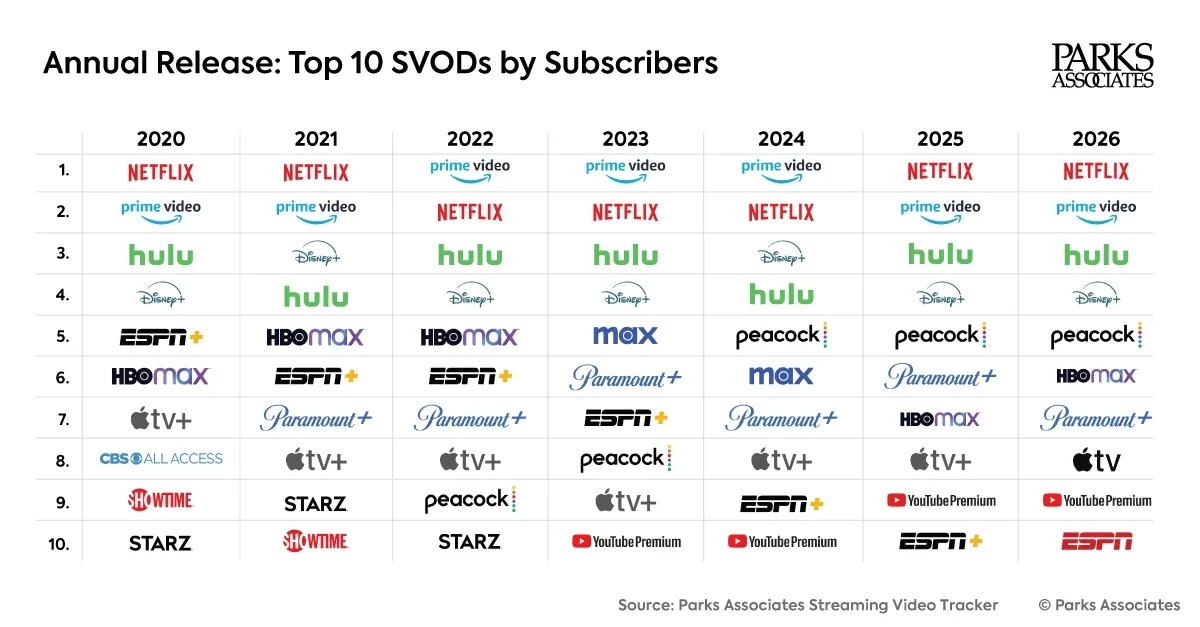
The 2026 Top 10 US SVOD Services
Parks Associates’ annual ranking, based on estimated subscriber numbers through September 2026, highlights the services competing for a lasting position in those household budgets:
- Netflix
- Prime Video
- Hulu
- Disney+
- Peacock
- HBO Max
- Paramount+
- Apple TV+
- YouTube Premium
- ESPN Select
Netflix holds the top position for the second consecutive year, and the top five services retain their positions. HBO Max moves ahead of Paramount+ to rank sixth.
Advertising is central to subscription strategy
More than half of subscribers to every major streaming service measured in Parks Associates’ ad-tier analysis use an ad-supported tier. Adoption ranges from 51% for Netflix to 76% for Peacock, with Amazon Prime Video at 67%, HBO Max at 55%, Paramount+ at 65%, Disney+ at 58%, and Hulu at 69%.
These plans help providers reach households seeking affordable access. Their economics depend on both subscription fees and advertising revenue, making engagement and advertising performance increasingly important.
Providers must also protect the viewing experience. Expanding advertising inventory creates a need to attract advertiser demand while managing ad loads and repetition.
Bundles must create lasting value
Bundles can make larger subscription portfolios affordable and give consumers reasons to retain services. Providers must assess whether those offers generate additional revenue and stronger retention or discount subscriptions households would have purchased separately.
Distribution also shapes the economics
Approximately 30% of subscriptions originate directly through service websites; the remainder come through devices, app stores, bundles, and other channels. Parks Associates research points to a market where success increasingly depends on earning a durable place in the household budget. Strong content remains essential, supported by easier discovery, flexible pricing, and a viewing experience that encourages consumers to stay.
For ongoing streaming market intelligence, Parks Associates’ Streaming Video Tracker provides regularly updated data and insights on more than 300 North American streaming services. Contact Parks Associates to request additional information or a demonstration.